A $2,500 loan is a fixed-rate personal loan that pet owners often use to cover an emergency vet visit or surgery, and that households also use to replace a major appliance. At an estimated 24.99% APR, an 18-month term works out to about $168 a month.
Who Typically Needs a $2,500 Loan
Borrowers who need about $2,500 are usually facing one large, non-negotiable bill, most often an emergency veterinary procedure, where the provider expects payment at or near the time of care.
Pet emergencies are especially hard on budgets because they combine urgency, emotion and upfront payment. An emergency clinic may require a deposit before surgery, and many animal hospitals do not bill later the way human medical providers often do. The typical personal loan borrower at this size has a dog or cat they consider family, steady income, and a savings account that covers routine checkups but not a foreign-body surgery or a fractured leg.
The second common profile is the household whose refrigerator, washer or range has quit. A mid-range refrigerator with delivery and haul-away can exceed $1,500, and a washer-and-dryer pair often costs more. Replacing both at once, or replacing one while repairing another, pushes the total into the $2,500 range.
People who search for stax payments at this level are usually comparing a personal loan with a veterinary credit card, a clinic payment plan or a general credit card. A fixed personal loan provides one known payment and an end date, which helps when you are also absorbing follow-up visits, medications and special food.
Using a $2,500 Loan for Emergency Vet Bills
A $2,500 loan can cover many emergency and surgical vet costs, such as an exam, X-rays and bloodwork, an obstruction removal, wound repair after a dog fight, or treatment for a urinary blockage, plus first follow-up visits.
When your pet is hurt or sick, the clinic will usually provide a treatment estimate with a low and a high range. Ask the staff to walk through each line. Emergency estimates are often built to cover the worst case, and knowing which items depend on what the team finds can help you plan.
Questions to ask at the emergency clinic
- What is the deposit required to start treatment, and when is the balance due?
- Which items are essential now, and which could be done later at your regular vet for less?
- Does the clinic accept a payment plan or third-party financing, and what are the terms?
- Can prescriptions be filled at an outside pharmacy at a lower price?
- If your pet is insured, will the clinic submit the claim, or do you pay first and get reimbursed?
Pet insurance usually reimburses after you pay, which is where a loan can bridge the gap. If your policy covers 80% after a deductible, you may get a sizable reimbursement weeks later. With no prepayment penalty, that check can go straight to principal and shorten the loan considerably.
Speed matters too. Many lenders fund as soon as the next business day after signing, though nothing about timing is certain and bank processing varies. Some clinics will begin stabilizing care while you arrange funding, so ask.
A Worked Example: Surgery for a Beagle Who Ate a Sock
A realistic surgery example shows how a $2,500 personal loan fits an emergency vet bill: the estimate, the deposit, the insurance reimbursement and the payment schedule that follows at a common estimated APR.
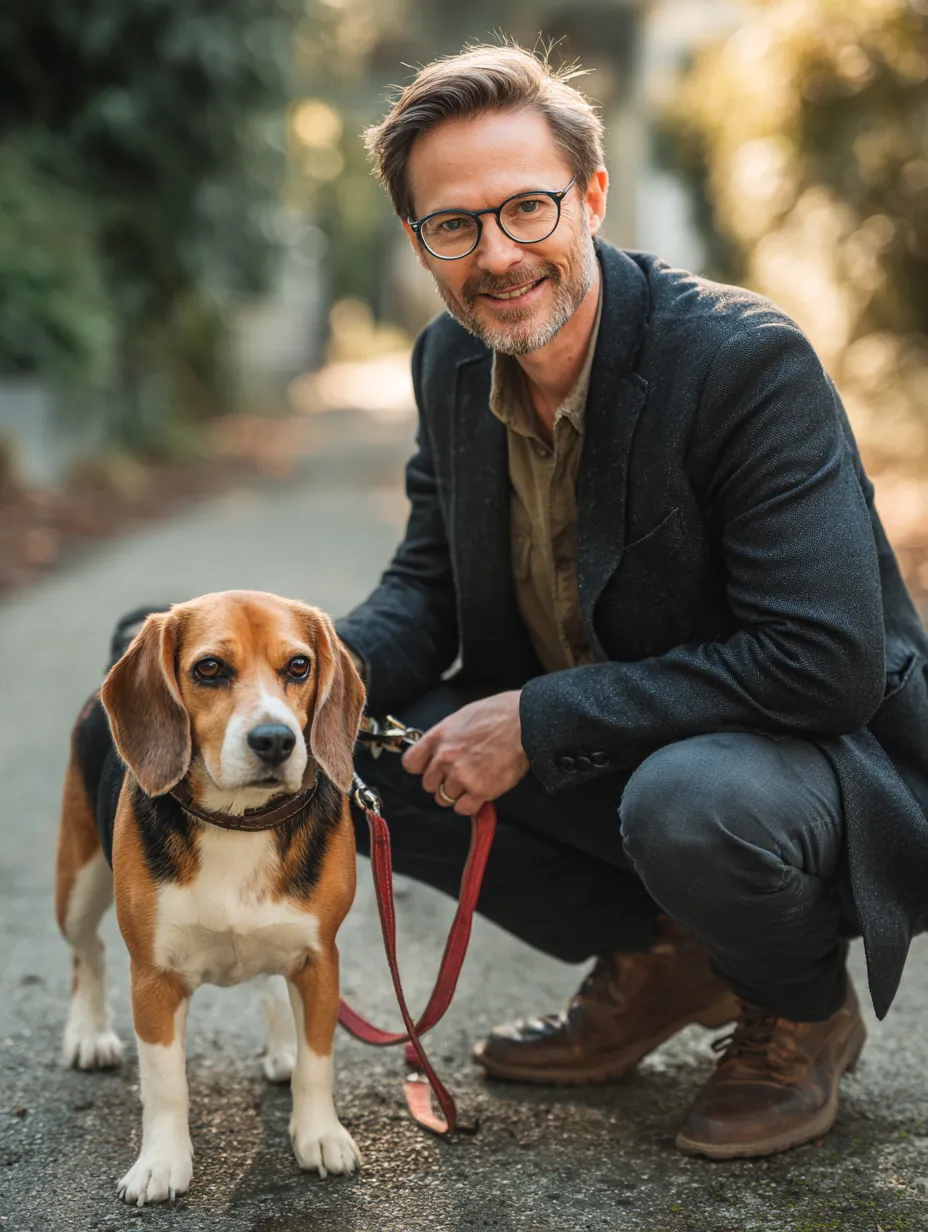
A man in his 30s notices his beagle vomiting and refusing food. X-rays at the emergency clinic show a sock lodged in the intestine. The estimate for surgery, anesthesia, two nights of hospitalization and medications ranges from $2,800 to $3,600. The owner has $600 in savings he can spare and asks the clinic which line items could be moved to his regular vet. Suture removal and the recheck exam can be, which trims about $150.
He requests $2,500 to cover the gap. At an estimated 24.99% APR over 18 months, the payment would be about $167.97 a month, with an estimated total of $3,023.41 repaid. Six weeks later, his insurer reimburses $1,200. He sends the full amount to the loan as extra principal, which shortens the schedule by many months and cuts total interest by hundreds of dollars.
His beagle recovers well. He puts a leash on the beagle for every walk now, keeps socks off the floor, and sets aside $40 a month in a pet fund once the loan is paid off.
Replacing a Major Appliance With a 2500 Dollar Loan
A 2500 dollar loan can also replace a major appliance such as a refrigerator, a washer-and-dryer pair or a range, especially when one failure happens soon after another and savings cannot cover both.
Before you buy, check whether a repair is reasonable. A refrigerator that stopped cooling may need only a defrost heater or a start relay, often a few hundred dollars. A common rule of thumb: if the repair costs more than half the price of a comparable new unit, and the appliance is past the middle of its expected life, replacement usually makes more sense.
- Compare scratch-and-dent or open-box models, which can save a meaningful amount with full warranty.
- Ask whether delivery, installation and haul-away are included, since they can add a noticeable sum.
- Check for utility rebates on efficient models.
- Look at the energy guide label; lower operating costs help offset the payment.
Store financing is common for appliances, and some promotional plans carry deferred interest charged back to the purchase date if the balance is not cleared on time. A fixed-rate personal loan does not have that feature, so compare the two on total cost.
When two appliances fail close together
Appliance failures tend to cluster in homes where everything was installed at the same time. A family that moved into a house with a matching refrigerator, washer and dryer may see all three reach the end of their lives within a couple of years. If the washer fails in spring and the refrigerator in summer, a household that paid cash for the first may need a personal loan for the second. Keeping a simple list of each appliance's purchase date helps you see these clusters coming and start saving before the second failure.
When you do borrow, keep the personal loan tied to the essential replacement. A refrigerator protects your grocery budget and a washer saves laundromat trips, so both pay you back in part. Upgrades like a second freezer or a smart display panel are better bought later from savings.
Estimated Payments on a $2,500 Loan
Estimated payments on a $2,500 loan at 24.99% APR range from about $448 a month on a 6-month term to about $99 a month on a 36-month term, with 18 months landing near $168.
The figures below use fixed-rate, fully amortizing personal loan math with no origination fee assumed, and every number is an estimate. Your lender sets the actual APR, fees and term. You can try other rates in our loan payment calculator.
| Term | Est. monthly payment (24.99% APR) | Est. total repaid | Est. interest |
|---|---|---|---|
| 6 months | $447.56 | $2,685 | $185 |
| 12 months | $237.60 | $2,851 | $351 |
| 18 months | $167.97 | $3,023.41 | $523 |
| 24 months | $133.42 | $3,202 | $702 |
| 36 months | $99.39 | $3,578 | $1,078 |
If a lender charges an origination fee, it may be 0%–10% of the amount, which raises the APR. A 4% fee on $2,500 is $100, so if the clinic needs the full $2,500, confirm whether the fee is deducted from your funds before you sign.
How Term Length Changes the Total Cost
At 24.99% APR, interest on $2,500 grows from about $351 over 12 months to about $1,078 over 36 months, so tripling the term roughly triples the interest you pay for the same vet bill or appliance.
The payment-versus-cost trade is easiest to see in steps. Moving from 12 to 18 months lowers the payment by about $70 and adds about $172 in interest. Moving from 18 to 24 months lowers it another $35 and adds about $179. Moving from 24 to 36 months lowers it about $34 but adds nearly $376. Each step buys less relief at a higher price.
When you expect an insurance reimbursement, a longer term with a lower required payment plus a planned lump-sum payoff can be a smart combination. You keep the monthly budget comfortable in the weeks after the emergency, then shrink the balance when the check arrives. Our page on personal loan APR ranges and rate factors explains why your offer may be higher or lower than this example.
Caution: pet insurance often excludes pre-existing conditions and may have waiting periods. Confirm what your policy will reimburse before counting on it to pay down the loan.
What Lenders Commonly Ask For at $2,500
At $2,500, lenders commonly verify identity, income, bank account details and credit history, and they look at your existing monthly debts to judge whether one more payment is affordable.
Expect to provide a government-issued photo ID, recent pay stubs or bank statements, a checking account in your name and your Social Security number. Some lenders ask for employer contact details or extra statements at this size, especially for self-employed applicants.
- Photo ID and a current address.
- Proof of steady income for at least the last month or two.
- Bank and routing numbers for deposit and autopay.
- The clinic's written estimate or the appliance quote, so you request the right amount.
Credit history matters more at this size than it does for smaller personal loans, because the lender's exposure is larger. Pulling your free credit reports from Equifax, Experian and TransUnion before you apply lets you spot errors, such as a paid account still showing a balance, and dispute them. Many lenders show estimated offers after a soft inquiry, which does not affect your score, and run a hard inquiry only if you choose to move forward with a specific personal loan offer.
Lenders consider credit score, payment history and debt-to-income ratio. Bad credit personal loans may still be available at this size, but expect higher APRs. Before applying, review our personal loan eligibility requirements. A stax payments request through our form is free and carries no obligation, and the lender, not our service, makes the credit decision.
$2,000, $2,500 or $5,000: Sizing the Request
Choose $2,500 when your estimate, after savings and trimmed items, lands between about $2,100 and $2,700; go smaller for a single repair, and consider $5,000 only for a complex, multi-day case or several large costs at once.
A minor injury, an ear infection or one dental extraction for a pet rarely needs this much. A single appliance repair may fit a $2,000 loan for home system repairs, which has an estimated 12-month payment of about $190 at 24.99% APR. A complex orthopedic surgery, cancer treatment or several costs at once can exceed $3,000; in that case, compare offers carefully, because a $5,000 balance doubles the payment and the interest.
Whatever you choose, borrow against the realistic middle of the estimate, not the absolute top, if you have some savings to cover overruns.
Alternatives for Vet Bills and Appliance Costs
Alternatives worth checking include a clinic payment plan, a veterinary credit card with a clear promotional term, nonprofit pet assistance funds, pet insurance reimbursement, appliance store financing and credit union loans.
Some animal welfare organizations offer grants or low-cost care for qualifying owners, and veterinary schools may provide treatment at reduced rates. A vet credit card can work if you are sure you can clear the balance before the promotion ends; deferred interest can make it expensive otherwise. For appliances, retailers sometimes match prices, and a scratch-and-dent unit may cut the cost enough to avoid borrowing at all.
When comparing personal loans online with these options, focus on total cost. Some people who begin with a stax payments search combine a smaller loan with an insurance reimbursement and a clinic plan for follow-up care.
Planning Repayment After a Pet Emergency
An effective repayment plan after a pet emergency budgets for follow-up care, applies any insurance reimbursement to principal, and starts a pet fund so the next vet visit is paid from savings instead of a loan.
Surgery is rarely the last bill. Rechecks, medications and special diets can continue for weeks. Build those costs into your budget alongside the loan payment, and set the due date a few days after your paycheck lands.
- List expected follow-up costs from the discharge instructions.
- Enroll in autopay to avoid late fees while you are busy caring for your pet.
- Send every insurance reimbursement straight to the balance.
- Once paid off, move the former payment into a dedicated pet fund.
If your pet has a chronic condition such as allergies, diabetes or arthritis, add the monthly medication and food costs to your budget as a fixed line, just like the loan payment. Ask your regular vet whether a wellness plan that spreads routine care across monthly installments would cost less than paying visit by visit. Predictable care costs make it easier to keep every loan payment on time.
A pet fund of even $1,000 changes how the next emergency feels, and it is the most effective way to make sure the next stax payments search is optional.
Next Steps for a Vet or Appliance Bill
Before requesting funds, get the written estimate, subtract savings and items that can wait, confirm any insurance reimbursement, and gather your ID, income records and bank details so a lender can review quickly.
When offers arrive, compare APR, fees, term and total repayment. Choose the shortest term that fits, and confirm early payoff carries no penalty so reimbursements can reduce the balance. We are a free connection service and do not set rates or approve applications; final terms come from the lender, and you can decline any offer. A clear estimate and a right-size personal loan let you focus on your pet's recovery or getting the kitchen working again.
Frequently Asked Questions
Can a $2,500 loan pay an emergency vet clinic before pet insurance reimburses me?
Yes, that is a common use. Most pet insurance reimburses after you pay the clinic, so a loan can bridge the gap. If your loan has no prepayment penalty, you can send the reimbursement straight to the balance and cut the total interest you pay.
What is the estimated monthly payment on $2,500 over 24 months?
At an estimated 24.99% APR with no origination fee, a 24-month term works out to about $133.42 a month, or roughly $3,202 repaid in total. Your actual payment depends on the APR, fees and term the lender offers after reviewing your application.
Is a 2500 dollar loan better than a veterinary credit card?
It depends on how fast you can repay. A vet card with a promotional rate can cost less if you clear it in time, but deferred interest may apply if you do not. A fixed-rate loan has a set payment and end date. Compare total cost both ways.
Should I repair or replace a broken refrigerator with borrowed money?
Get a repair quote first. If the repair costs more than about half the price of a comparable new unit and the fridge is past mid-life, replacement often makes more sense. Borrow only for the option you choose, and check for rebates or open-box discounts.